How to Start a Prop Firm: Model and Legal Risks
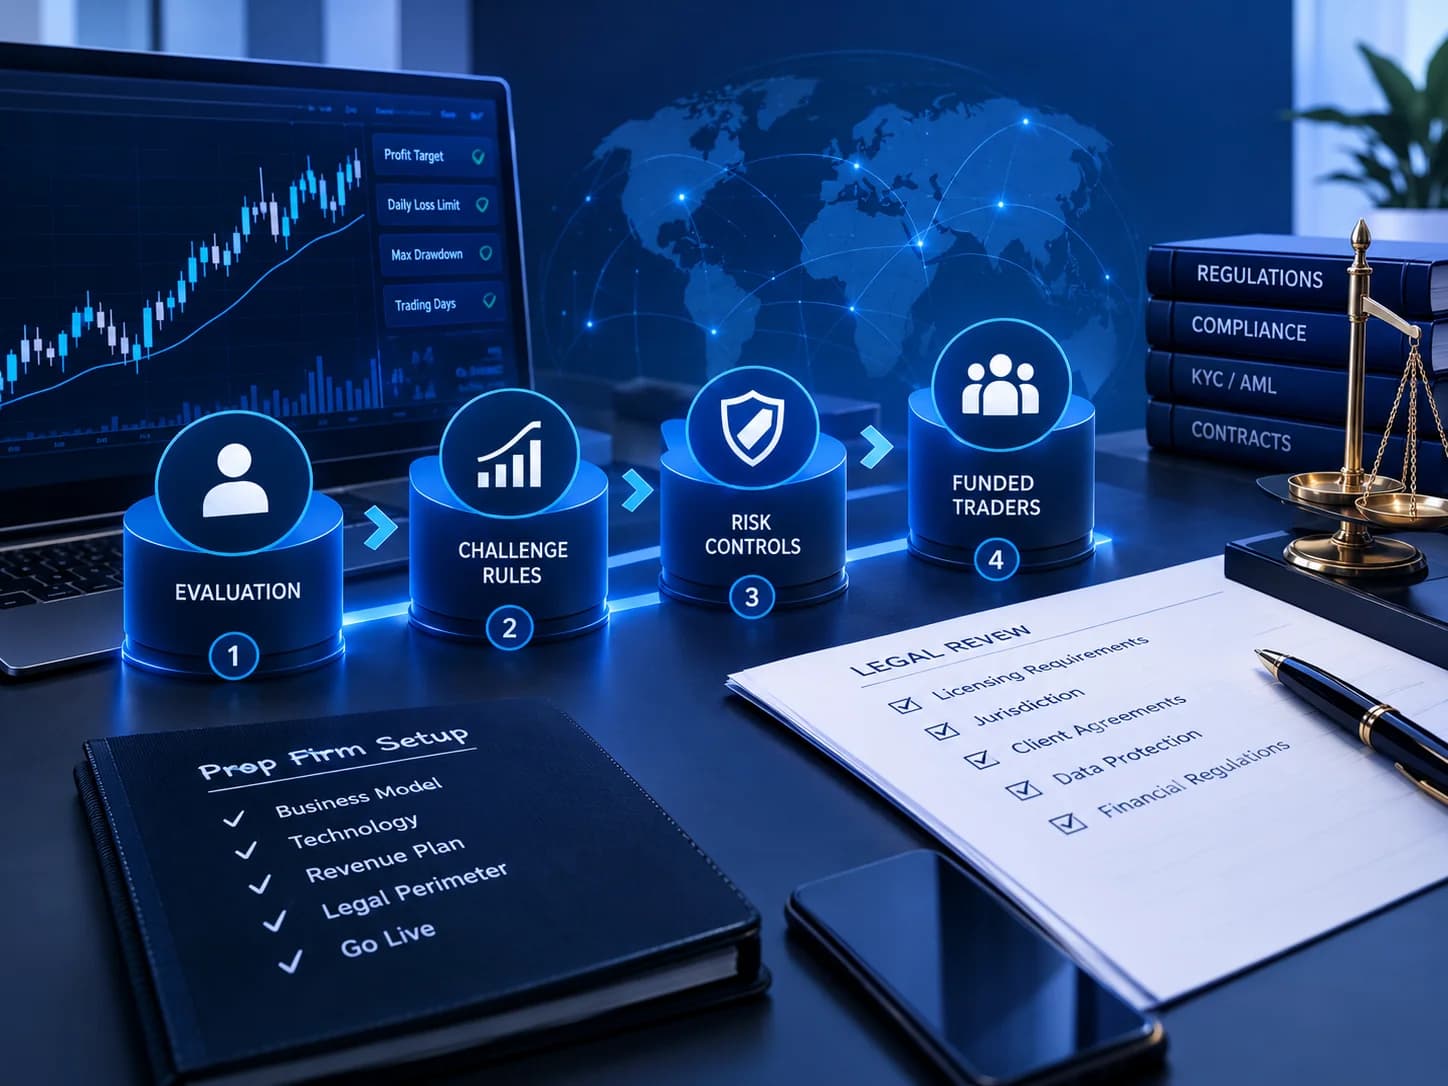
To start a prop firm, define the evaluation business model and legal perimeter before choosing software, payment tools, or a white-label platform. The central question is what customers buy, what is simulated, where orders execute, and what creates an obligation to pay. Treat the plan as an operational and legal design exercise, not a platform purchase.
How to start a prop firm : definition and decision?
Start by identifying the activity the business will actually perform, then map its contracts, money flows, technology, and controls to that activity. A useful starting point is to ask whether the operation trades its own capital, sells a simulated evaluation and reward service, or handles customer-facing financial activity.
The available research does not establish a universal licensing answer for every jurisdiction. It does support a narrower conclusion: prospective founders should learn which firms are licensed, why many are not, and how to vet a provider before paying a fee. That framing is attributed to the cited 2026 research rather than presented as a general legal rule the 2026 regulation guide.
For a US-facing planning process, treat this as a scoping document rather than a legal opinion. The business description should be precise enough for counsel, compliance advisers, payment partners, and technology vendors to review. A Platform overview can help organize the technology discussion, but it cannot decide the legal perimeter.
Who should consider how to start a prop firm: evaluation business model and legal perimeter?
This model deserves consideration from founders who are prepared to define the commercial activity before selecting a stack. The decision is less about finding a dashboard and more about documenting what participants purchase, what balances represent, and what events create a payment obligation.
EverFunded’s September 19, 2026 editorial makes that sequencing its first practical point: define the actual business activity before selecting a platform the September 2026 planning guide. Its stated planning approach combines business-activity definition with regulatory checks, cash obligations, vendor testing, and launch criteria the launch-controls discussion.
That sequence is useful for a founder comparing a white-label arrangement with a more tailored operating stack. Begin with a written business-model statement. Describe who supplies money, who owns any position, where an order executes, whether a balance is simulated, what a participant purchases, and what can become payable. Then ask advisers and vendors to respond to that same description. If the description changes, the technology and documentation review should change with it.
Do not use a label such as “funded account” as a substitute for those facts. The cited planning guide specifically cautions that an advertised account size may be a simulation parameter rather than cash allocated to an individual trader the simulated-balance caveat. A Forex white label may be relevant to platform planning, but its presence does not answer the underlying business-model questions.
Benefits and practical limitations
An evaluation structure can give a founder a clear way to describe participation, rules, records, and potential rewards. It can also create a defined checklist for customer terms, account states, payment handling, support processes, and exception management. Those are design benefits, not promises about commercial performance.
The practical limitation is that a polished interface can conceal unresolved questions. A simulated balance is not the same thing as operating cash. A payment event is not automatically explained by a marketing label. A trading rule is not automatically a customer term, accounting treatment, or compliance control. Each item needs a place in the operating model and a responsible owner.
There is also a source-quality limitation. The available research is educational and unverified rather than regulator-issued, audited, or a jurisdiction-specific legal opinion. It can support planning questions and cautions, but it cannot establish that a particular structure is lawful in a particular location. Keep that distinction visible in internal approval documents and external copy.
A balanced launch plan therefore has two tracks. One track describes the participant journey from registration through evaluation, rule enforcement, payout review, dispute handling, and account closure. The other tracks cash obligations, records, vendors, permissions, and professional advice. A Prop firm software review should sit inside those tracks rather than replace them.
prop firm crm and the reader decision
A CRM decision should follow the operating model. Start by listing the records the business must create and retrieve, then test whether a proposed system can support those records without changing the commercial description. The goal is traceability: a team should be able to connect an applicant, agreement, evaluation state, payment, rule event, support case, and final decision.
Keep the CRM discussion separate from unsupported feature comparisons. The approved research does not establish that any named CRM has a particular integration, automation, capacity, price, or compliance function. Those details require product documentation and a controlled technical review. Do not infer them from a generic white-label claim.
For an internal selection exercise, ask vendors to demonstrate the exact workflows that matter to the business. Include registration, identity checks where applicable, payment status, rule changes, manual review, appeals, payout approval, and record export. Ask which actions are logged, who can change a rule, how changes are communicated, and how historical records are preserved.
Use a API docs review only after the process map is agreed. Technical connectivity is useful when it serves a defined control or operational handoff. It is not a substitute for deciding what the firm offers or how the customer relationship is documented.
Suitable forex crm for prop firms and the reader decision
The suitable system is the one that fits the documented participant journey, control requirements, and review responsibilities. Avoid choosing from a feature list alone. A founder should first decide whether the operation needs a simple evaluation record, a broader brokerage workflow, or a connected stack spanning payments, identity processes, customer support, and reporting.
That distinction matters because the sources describe different business activities rather than one universal prop-firm template. The planning guide separates an own-capital trading desk, a simulated evaluation and reward service, and customer-facing financial activity as questions requiring different evidence before launch the business-model examples. Use those categories as prompts for counsel and operations teams, not as automatic legal classifications.
The regulation-focused source also frames the issue around the perimeter that applies to the model and the protections available if terms change after a fee is paid the perimeter question. That makes customer terms, change control, dispute handling, and transparent communications part of the technology conversation. A Payment infrastructure review should therefore cover reconciliation and records as well as the payment page.
Before approving a vendor, require a written demonstration of the workflows, data ownership, permissions, audit trail, support process, and exit plan. Ask for the assumptions behind every “funded” label, advertised balance, rule, and reward description. If the vendor cannot explain how the system reflects the approved business model, pause the selection.
Conclusion
Learning how to start a prop firm begins with classification and documentation, not a platform order. Define the evaluation model, describe the legal perimeter for the actual activities, and separate simulated balances from cash obligations. The cited planning source recommends defining the business activity before selecting software the activity-first recommendation.
Next, turn that description into customer terms, operational controls, payment workflows, CRM records, and vendor tests. Treat regulation as a jurisdiction-specific review rather than a marketing label. The available regulation-focused source emphasizes vetting the provider and asking what perimeter applies to the business model the provider-vetting guidance.
Finally, use technology to implement an approved operating design. A Licensing & compliance discussion may help structure questions for qualified advisers, while Get started can be a next-step contact route for technology questions. Neither replaces legal, licensing, or compliance advice.
Sources
- Prop Firms Regulation: A Trader's Honest Guide — myfundedcapital.com, 2026-07-27T08:32:56.000Z
- How to Start a Prop Firm: Business Model, Cash and Launch Controls — everfunded.com, 2026-09-19T06:37:55.000Z
Frequently Asked Questions
What should a new prop firm define before selecting software?
Define the actual business activity first: what participants purchase, whether balances are simulated, where orders execute, who owns positions, and what creates a payment obligation. The cited planning guide recommends this sequence before choosing a platform, while noting that an advertised account size may be a simulation parameter rather than cash allocated to a trader.
Does a white-label platform settle the legal perimeter?
No. A white-label platform can be part of a technology plan, but it does not by itself determine the business activity, customer terms, payment obligations, or jurisdictional requirements. The available research advises founders to define the model and seek qualified jurisdiction-specific advice rather than treat a platform label as a legal conclusion.
How should a founder review a prop firm provider?
Review the provider against the business model, customer terms, rule-change process, payment handling, records, support, and dispute process. The regulation-focused source frames due diligence around the applicable perimeter and how participants are protected if terms change after payment.