Prop firm payout automation: eligibility review and approval controls
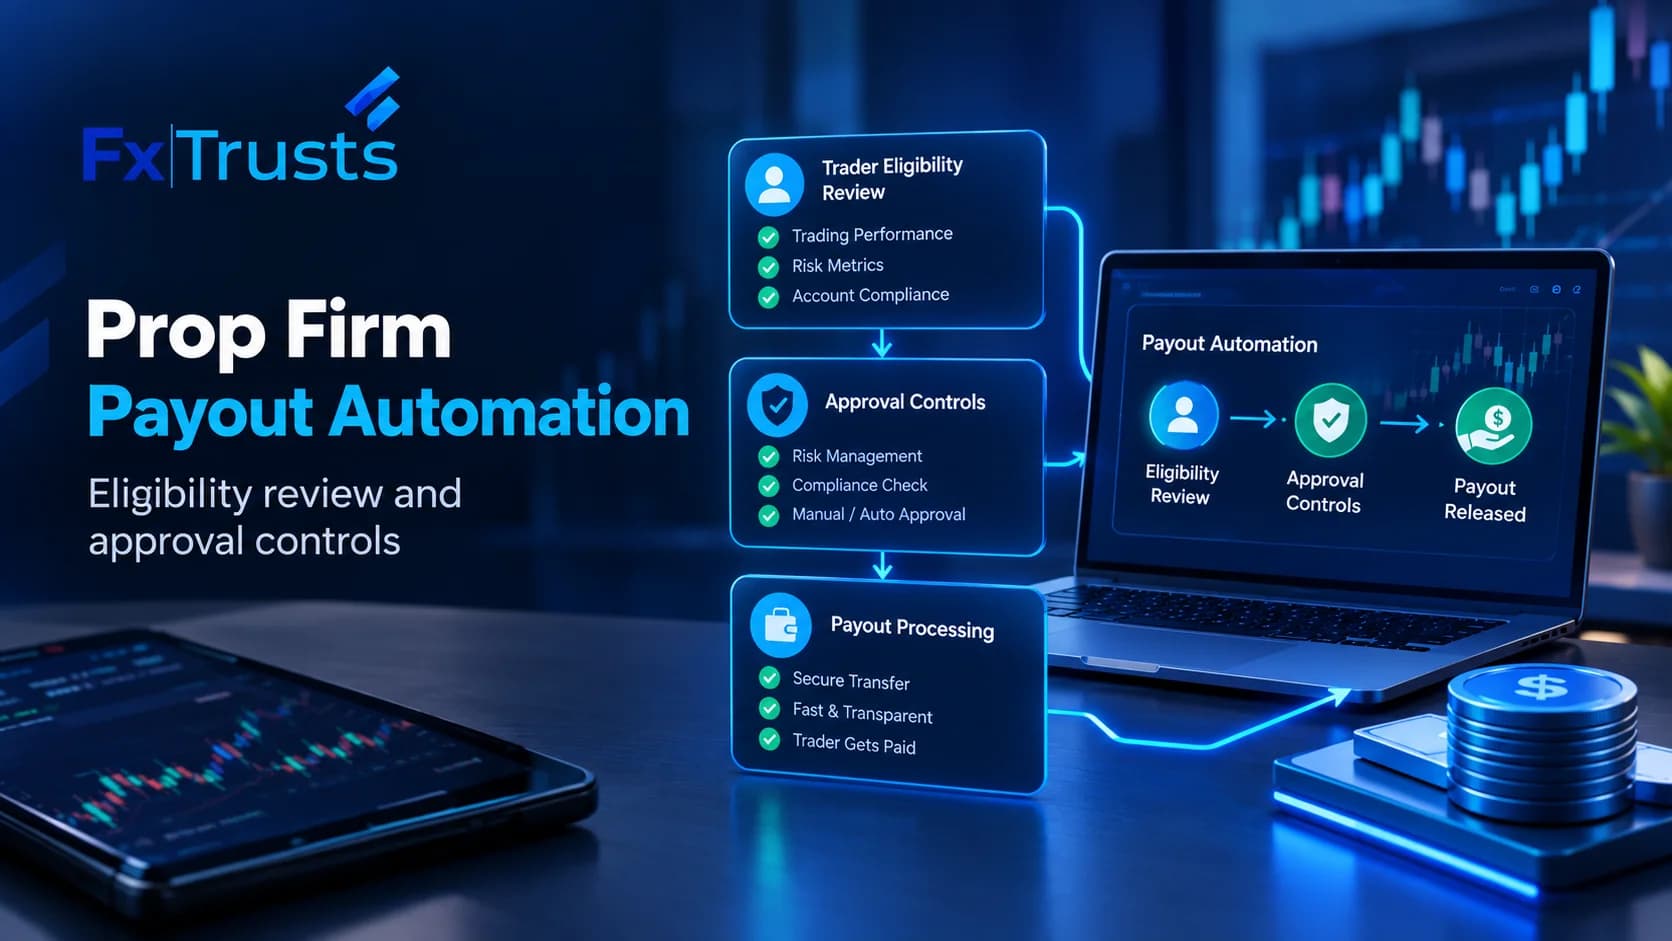
Prop firm payout automation: eligibility review and approval controls should turn written rules into a reviewable workflow, not remove human judgment. The practical model separates eligibility checks, exception handling, approval authority, and payment release. Clear records matter. Any workflow should also reflect the firm’s compliance responsibilities and documented risk controls.
Prop firm payout automation: eligibility review and approval controls
Prop firm payout automation: eligibility review and approval controls means designing a workflow that checks a payout request against documented conditions before money is released. It does not mean treating an automated result as an unquestionable decision. The workflow should show what was checked, which rule was applied, whether an exception occurred, and who authorised the next stage.
A useful design begins with a plain-language policy. The policy should distinguish conditions that can be checked consistently from matters that need an investigation. It should also define what happens when information is incomplete, contradictory, or unavailable. That distinction keeps the workflow from presenting a missing record as a failed eligibility decision.
The decision is therefore operational rather than promotional. A firm can consider automation when it needs repeatable handling and clearer ownership, but it should first document the decisions the system is expected to support. Platform overview can be used as a contextual next step for teams mapping their wider operating model.
Prop firm payout automation eligibility review and approval controls?
Teams should consider this approach when payout requests are becoming difficult to review consistently or when responsibilities are unclear. It may suit an operator that wants a common process for intake, review, escalation, approval, and release. The decision should follow a process review, not a presumption that automation is appropriate for every case.
Early-stage firms may need a simple documented checklist before they need a complex system. More established operators may focus on permissions, audit visibility, exception queues, and the connection between participant records and payment operations. In either case, the operating question is the same: can an authorised person understand why a request moved forward or stopped?
A platform conversation should remain specific about the firm’s process. Teams can compare the workflow with their wider Prop firm software requirements, while keeping eligibility policy, compliance review, and payment decisions under appropriate internal ownership.
Benefits and practical limitations
Automation can make a defined process easier to repeat, but its value depends on the quality of the rules and records behind it. A consistent sequence can reduce ambiguity between teams, make pending cases easier to locate, and give reviewers a common place to examine the decision history. Those are process benefits, not evidence of financial performance.
Potential benefits
- Rules can be presented in a consistent sequence.
- Exceptions can be separated from routine cases.
- Approval ownership can be made visible.
- Decision records can support later review.
Practical limitations
- Incomplete rules can produce consistent but unsuitable outcomes.
- Exceptional cases still require human assessment.
- Access permissions can create control weaknesses if poorly designed.
- Payment release should not be treated as proof that every underlying issue is resolved.
The central safeguard is reviewability. A firm should be able to amend a rule through a controlled process, identify affected cases, and explain the change to an authorised reviewer. Automation is less useful when it hides the policy behind a status label that no one can interpret.
Yopips review and the reader decision
A reader assessing any prop-firm payout process should focus on how eligibility is defined rather than relying on a simple approval label. The relevant questions concern the written rules, the evidence collected, the handling of exceptions, and the separation between reviewing a request and releasing a payment.
The same framework applies when evaluating a named firm, service, or workflow. A review should distinguish published policy from observed operation and should avoid turning an interface description into a claim about reliability or outcomes. Without verified evidence, the responsible conclusion is limited: the process can be assessed for clarity and control design, but not for results that the available material does not establish.
That distinction is especially useful for teams comparing their own operating needs with an external workflow. The reader can document required checks, define escalation points, and then ask whether the proposed system supports those requirements. A relevant internal resource is Payment infrastructure, considered as part of a broader process rather than as a substitute for policy ownership.
Suitable crm for established prop firms and the reader decision
A suitable CRM workflow for an established prop firm should be judged by how clearly it connects participant information, eligibility review, case status, permissions, and approval history. The label alone is not enough. Operators should map the records needed by each decision and identify which users may view, amend, approve, or escalate a case.
Integration can be useful, but integration does not remove the need for governance. A firm should establish who owns the policy, who checks exceptions, who can change workflow conditions, and who can authorise release. It should also decide how unresolved cases are represented so that a pending review is not mistaken for a completed approval.
Teams may use API docs when they are assessing technical connections, but technical access should be considered alongside permissions and operational accountability. For broader stack planning, Licensing & compliance provides a relevant internal context without replacing qualified professional advice.
Conclusion
Prop firm payout automation is best treated as a controlled operating workflow: define eligibility, collect the relevant record, route exceptions, assign approval authority, and release payment only after the required review. That sequence keeps automation in a supporting role and leaves accountable people responsible for policy and exceptional decisions.
The approach is not a shortcut around compliance, payment governance, or risk management. It is a way to make an existing process more visible and repeatable when the underlying rules are clear. Before selecting or configuring a system, document the decision path and test how it handles incomplete information and cases outside the normal route.
Operators can then compare those requirements with their broader Forex white label or infrastructure plans. The appropriate next step is a documented review with qualified legal and compliance professionals where jurisdictional obligations or customer-facing decisions are involved.
Sources
Frequently Asked Questions
Which crypto gateway should a new prop firm evaluate?
A new prop firm should evaluate a gateway against its documented payout policy, participant verification process, exception handling, permissions, settlement workflow, and recordkeeping needs. No single gateway can be selected responsibly from the available research bundle, so the decision requires a review of the firm’s jurisdiction, controls, and operating requirements.